Tag: first home buyers

First home buyers in Melbourne’s Inner North, deposit schemes, buying tips and local guides from Buyer’s Agent Victoria.

  • Cooling Off Period in Victoria: How It Works and When You Get None

    Cooling Off Period in Victoria: How It Works and When You Get None

    The cooling off period in Victoria gives you 3 clear business days after you sign a private sale contract to change your mind and walk away. It isn’t free. You lose $100 or 0.2% of the price, whichever is more, and it doesn’t apply at all if you buy at auction or close to one.

    Below I cover how long the cooling off period is, what it costs, how to use it, the 5 situations where you don’t get one, and why I’d rather you never need it.
    Cooling off period in Victoria: 3 business days, and when you get none

    Key points

    • You have 3 clear business days from the day you sign, not the day the seller signs.
    • Weekends and public holidays don’t count, so Melbourne Cup Day can push your deadline out.
    • Cooling off costs the greater of $100 or 0.2% of the price. On an $800,000 home that’s $1,600.
    • You cool off by giving written notice to the seller or the seller’s agent. You don’t need a reason.
    • There’s no cooling off at auction, within 3 clear business days before or after an advertised auction, or when you buy through a company.

    Buying in Melbourne’s North in the next few months? I have 3 Foundation Client places at half my standard fee. Answer 7 questions to see if you fit.

    How Long Is the Cooling Off Period in Victoria?

    It’s 3 clear business days, under section 31 of the Sale of Land Act 1962. Consumer Affairs Victoria says the period starts from the date you sign the contract, not the date the seller signs it. It covers residential property, and rural property under 20 hectares, bought by private sale.

    “Clear” means the day you sign doesn’t count. Saturdays, Sundays and public holidays don’t count either. Melbourne Cup Day, Tuesday 3 November 2026, is a public holiday in metropolitan Melbourne, so a contract signed on Monday 2 November gives you Wednesday, Thursday and Friday. Ask your conveyancer to confirm the exact deadline the day you sign.

    How Much Does It Cost to Cool Off?

    If you cool off, the seller can keep $100 or 0.2% of the purchase price, whichever is greater. Everything else you’ve paid comes back to you. At Inner North prices, 0.2% is always the bigger number:

    • $600,000 apartment: $1,200
    • $800,000 townhouse: $1,600
    • $1,200,000 house: $2,400

    That’s a real cost, though it’s small next to buying the wrong property. It also doesn’t cover any money you’ve spent on inspections or legal fees before you pulled out.

    How Do You Cool Off on a Property in Victoria?

    You give written notice to the seller or the seller’s agent before the period ends. You don’t have to give a reason. Email works, but get confirmation that it was received, and keep a copy.

    Tell your conveyancer before you send anything. They can word the notice, check the deadline and deal with the refund of your deposit, less the amount the seller is allowed to keep.

    When Doesn’t the Cooling Off Period Apply? 5 Exceptions

    Consumer Affairs Victoria lists the situations where you have no right to cool off. These are the ones that catch buyers out:

    1. You buy at auction, or close to one

    There’s no cooling off when you buy at a public auction. It also doesn’t apply if you sign within 3 clear business days before or after a publicly advertised auction. That includes buying the property before auction day, or negotiating with the agent after it’s passed in. See CAV’s guide to buying at auction.

    2. The property is mainly commercial or industrial

    Shops, offices and warehouses used mainly for commercial or industrial purposes don’t carry a cooling off period.

    3. It’s a farm over 20 hectares

    Farming land over 20 hectares, used mainly for farming, is excluded.

    4. You signed a contract for the same property before

    If you previously signed a contract for the same property on substantially the same terms, you don’t get a second cooling off period.

    5. You’re an estate agent or you buy through a company

    Cooling off doesn’t apply when the buyer is an estate agent or a corporate body. If you’re buying through a company, including a self-managed super fund with a corporate trustee, plan on having no cooling off period at all.

    One rule you may still see in older guides: getting legal advice before you sign no longer takes away your right to cool off. That exception was removed in 2012.

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    Is a Cooling Off Period the Same as a Finance or Building Clause?

    No. Cooling off is a right the law gives you on most private sales, and it ends after 3 clear business days whatever happens. A finance clause or a building inspection clause is a special condition you negotiate into the contract, with its own deadline and its own terms.

    If your loan approval or building report won’t be ready within 3 business days, cooling off won’t protect you. Ask for the condition in the contract before you sign, and have your conveyancer check the wording.

    What I Tell Buyers Before They Sign a Private Sale

    Treat cooling off as a safety net, and do your checks before you sign. On a $1.2 million Preston house, changing your mind costs $2,400, and at auction you can’t change your mind at all.

    Before my clients sign, their conveyancer has read the section 32 and the contract, they have pre-approval from their lender, and the building inspection is done or written into the contract. If you’re buying your first home, my first home buyer guide covers the schemes and the steps to take before you inspect.

    Frequently Asked Questions

    How long is the cooling off period in Victoria?

    3 clear business days from the day you sign the contract. The day you sign, weekends and public holidays don’t count.

    How much do you lose if you cool off in Victoria?

    The seller can keep $100 or 0.2% of the purchase price, whichever is greater. On an $800,000 property that’s $1,600. The rest of what you’ve paid is refunded.

    Is there a cooling off period at auction in Victoria?

    No. There’s no cooling off if you buy at a public auction, or if you sign within 3 clear business days before or after a publicly advertised auction.

    How do I cool off on a property contract?

    Give written notice to the seller or the seller’s agent before the 3 clear business days end. You don’t need to give a reason. Speak to your conveyancer first and keep proof the notice was received.

    Does the cooling off period apply if I buy through a company?

    No. Cooling off doesn’t apply when the buyer is a corporate body or an estate agent, so a purchase through a company, including an SMSF with a corporate trustee, has no cooling off period.


    The cooling off period in Victoria is short and it costs money to use. Know your deadline the day you sign, and do the checks that matter before you sign rather than after.

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    Jason McCall is a licensed buyer’s advocate (licence 091847L) and the founder of Buyer’s Agent Victoria Pty Ltd (licence 091857L), based in Thornbury. He is a member of the REIV and PICA.
  • First Home Buyer in Victoria: Grants, Stamp Duty and What to Do First

    First Home Buyer in Victoria: Grants, Stamp Duty and What to Do First

    As a first home buyer in Victoria you can get real help: no stamp duty on a home up to $600,000, a $10,000 grant if you buy or build a new home, and a federal scheme that lets you buy with a 5% deposit. Knowing which of these you qualify for, before you start inspecting, changes what you can afford and where you should look.

    Below I cover each one, what the numbers mean for buyers in Melbourne’s North, five steps to take first, and the mistakes I see first home buyers make.

    Key points

    • First home buyers in Victoria pay no stamp duty on a home valued at $600,000 or less, and reduced duty between $600,001 and $750,000.
    • The $10,000 First Home Owner Grant is for new homes valued up to $750,000. Established homes don’t qualify.
    • Under the federal 5% Deposit Scheme, the price cap in Melbourne is $950,000, and there has been no income cap since 1 October 2025.
    • Get pre-approval and confirm your eligibility before you inspect, so you know your real budget.

    Buying in Melbourne’s North in the next few months? I have 3 Foundation Client places at half my standard fee. Answer 7 questions to see if you fit.

    First home buyer in Victoria guide to grants, stamp duty and first steps

    What Help Can a First Home Buyer in Victoria Get?

    There are three main kinds of help, and they work differently. Two come from the Victorian Government through the State Revenue Office. The third is a federal scheme run through Housing Australia and participating lenders.

    Stamp duty exemption and concession

    If you’re a first home buyer in Victoria and the home is worth $600,000 or less, you pay no land transfer (stamp) duty. Between $600,001 and $750,000 you pay a reduced amount, and above $750,000 you pay full duty. This applies to established homes as well as new ones, as long as you meet the State Revenue Office’s conditions, including living in the home as your principal place of residence.

    The $10,000 First Home Owner Grant

    The First Home Owner Grant is $10,000 for a new home valued up to $750,000. That includes building a new home, buying off the plan, or buying a home that hasn’t been lived in before. You need to live in it as your principal place of residence for at least 12 months. Buying an established house or apartment doesn’t qualify.

    The 5% Deposit Scheme

    Under the federal scheme, the government guarantees part of your loan, so you can buy with a 5% deposit without paying lenders mortgage insurance. Since 1 October 2025 there has been no income cap and no limit on places, according to Housing Australia. The property price cap is $950,000 in Melbourne and Geelong, and $650,000 in the rest of Victoria. You apply through a participating lender or broker.

    What Does That Mean in Melbourne’s North?

    It depends on what you’re buying. Hotspotting’s Suburb Report for Northcote (16 October 2026) puts the median house price at $1,653,000, well above every cap. The median unit price is $617,500, which sits just above the $600,000 full stamp duty exemption and well under the $950,000 cap for the 5% Deposit Scheme.

    For many first home buyers in the inner north, that means a unit or apartment is where the schemes do the most work. If you’re set on a house, the deposit scheme can still help with the deposit, but you’ll be paying full stamp duty, so plan for it.

    First Home Buyer in Victoria: 5 Steps Before You Start Looking

    1. Get pre-approval, and ask which schemes you qualify for

    A broker can tell you what you can borrow, whether you’re eligible for the 5% Deposit Scheme, and which lenders offer it. Check when your pre-approval expires, because they don’t last forever.

    2. Work out your total costs, not just the deposit

    Add stamp duty if it applies, conveyancing, a building and pest inspection, loan fees, insurance and moving costs. Your budget is the price you can pay after all of those, with a buffer left over.

    3. Write a one-page brief

    List your must-haves and your nice-to-haves. Most buyers have to give ground on one of four things: price, location, the dwelling or the land. Decide which one before you inspect, and decisions on the day get much easier.

    4. Learn the documents

    Ask for the Property Price Statement at every inspection, and read my guide to the section 32 so you know what to look for in the vendor statement. Have a conveyancer lined up before you find the place, so the contract can be checked quickly.

    5. Know the difference between auction and private sale

    There’s no cooling-off period when you buy at auction in Victoria. For most private sales you have 3 business days to cool off, but you lose $100 or 0.2% of the price, whichever is more. If you’re bidding, your finance and contract review need to be done before auction day.

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    What Mistakes Do First Home Buyers Make?

    • Assuming the $10,000 grant applies to an established home. It doesn’t.
    • Budgeting right up to a scheme cap, with nothing left for duty, fees or a rate rise.
    • Bidding at auction before the contract and section 32 have been read.
    • Letting pre-approval expire in the middle of the search.
    • Skipping the building and pest inspection to save a few hundred dollars.

    Should a First Home Buyer Use a Buyer’s Agent?

    Not every first home buyer needs one. If you have time to inspect every weekend, you’re comfortable negotiating with a selling agent and you know the area, you can do it yourself with a good broker and conveyancer.

    A buyer’s agent is worth it when you’re short on time, you keep missing out, or you’re buying somewhere you don’t know well. I act only for buyers, and I handle the search, the inspections, the negotiation and the run to settlement. My guide to off-market properties and my pre-settlement inspection checklist cover two stages first home buyers often ask me about.

    Frequently Asked Questions

    Do first home buyers pay stamp duty in Victoria?

    Not on a home valued at $600,000 or less, if you meet the State Revenue Office conditions. Between $600,001 and $750,000 you pay reduced duty, and above $750,000 you pay full duty.

    How much is the First Home Owner Grant in Victoria?

    It is $10,000 for a new home valued up to $750,000, and you need to live in it for at least 12 months. Established homes don’t qualify.

    What is the price cap for the 5% Deposit Scheme in Melbourne?

    The cap is $950,000 in Melbourne and Geelong, and $650,000 in the rest of Victoria. There has been no income cap since 1 October 2025.

    Can a first home buyer in Victoria use the stamp duty exemption and the 5% Deposit Scheme together?

    Yes, if you meet the conditions for each. The duty exemption comes from the State Revenue Office and the deposit scheme from Housing Australia through your lender, so check eligibility for both with your broker.

    What should a first home buyer in Victoria do first?

    Get pre-approval and confirm which schemes you qualify for, work out your total costs, write a one-page brief, and have a conveyancer ready before you start inspecting.


    Being a first home buyer in Victoria comes with real help, but only if you check your eligibility early and budget for everything the schemes don’t cover. Get pre-approval, write your brief, and have the documents checked before you sign or bid.

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    Jason McCall is a licensed buyer’s advocate (licence 091847L) and the founder of Buyer’s Agent Victoria Pty Ltd (licence 091857L), based in Thornbury. He is a member of the REIV and PICA. This article is general information, not financial advice. Check your eligibility with the State Revenue Office and your broker.
  • 5% Deposit Scheme: What It Actually Means for Inner North Buyers

    5% Deposit Scheme: What It Actually Means for Inner North Buyers

    The 5% Deposit Scheme just got bigger, and more first home buyers are using it than most people realise. According to Hotspotting’s Week In Real Estate (12 September 2026), over 120,000 first home buyer households have already used the expanded scheme to get into the market with a smaller deposit.

    That’s a national number, but the effect of it is entirely local. If you’re buying in Thornbury, Northcote or Preston, this changes who you’re competing against, not just what you can borrow.

    Buying in Melbourne’s North in the next few months? I have 3 Foundation Client places at half my standard fee. Answer 7 questions to see if you fit.

    What Is the 5% Deposit Scheme?

    The 5% Deposit Scheme (formally the Australian Government 5% Deposit Scheme, previously known as the Home Guarantee Scheme) lets eligible first home buyers purchase with as little as a 5% deposit, without paying Lenders Mortgage Insurance. Single parents and legal guardians can access it with a deposit as low as 2%.

    As of October 2025, the scheme carries no income caps and no waitlists, which is part of why uptake has accelerated so quickly. Applicants still need to meet standard lending criteria and apply through a participating lender, and the scheme applies within set property price caps that vary by location. For Melbourne, which includes Thornbury, Northcote and Preston, the cap is $950,000.

    Why Does This Matter If You’re Buying in the Inner North?

    More first home buyers able to move with a smaller deposit means more of them competing at the same time, for the same kind of property. In Thornbury, Northcote and Preston, that pressure lands squarely on the entry-level units and smaller houses that first home buyers are actually shopping for.

    In practice that means more people at the same open homes, more competing offers on the same shortlist, and less room to wait and see before making a decision.

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    Does Waiting to Save a Bigger Deposit Still Make Sense?

    For a lot of buyers, no. The logic behind saving a bigger deposit was always to reduce risk and avoid Lenders Mortgage Insurance. The 5% Deposit Scheme already removes the LMI cost for eligible buyers, so the main thing a longer savings period buys you now is more time for prices to move and more competition to show up at the properties you actually want.

    The real risk for a lot of Inner North buyers isn’t moving too early on a 5% deposit. It’s spending another 12 months saving while the pool of buyers competing for the same entry-level stock keeps growing.

    What Should First Home Buyers Actually Do With This Information?

    Three things worth doing before you assume the scheme changes your plans:

    Check your eligibility and the price cap for the specific area you’re looking at, since caps vary by location and a property just over the cap won’t qualify. Talk to a broker early, before you fall in love with a property, so you know exactly what you can borrow and under what terms. And get someone assessing properties on your side of the transaction, since more competition at the entry level is exactly when buyers are most likely to overpay or skip a proper inspection just to keep up.

    Frequently Asked Questions

    What is the 5% Deposit Scheme? It’s the Australian Government’s scheme (previously the Home Guarantee Scheme) that lets eligible first home buyers purchase a property with as little as a 5% deposit and no Lenders Mortgage Insurance, subject to price caps and lender approval.

    Who is eligible for the 5% Deposit Scheme? First home buyers generally need a minimum 5% deposit, while single parents or legal guardians can qualify with as little as 2%. As of October 2025 there are no income caps, though applicants still need to meet standard lending criteria through a participating lender.

    Does the 5% Deposit Scheme apply everywhere in Melbourne’s Inner North? Yes, as long as the property is priced at or below the cap. The cap for Melbourne is $950,000, and that covers Thornbury, Northcote and Preston. Caps can change, so confirm the figure with your lender for any property you’re considering.

    Is it better to save a bigger deposit instead of using the scheme? For many buyers, no. The scheme already removes the Lenders Mortgage Insurance cost that a bigger deposit was partly designed to avoid, and a longer savings period usually means more competition at the entry level of the market, not less.


    More first home buyers are moving sooner because of the 5% Deposit Scheme, and that means more competition across Thornbury, Northcote and Preston.

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    External source cited: Australian Government 5% Deposit Scheme, Housing Australia / First Home Buyers portal.

  • Is a Buyer’s Agent Worth It in Melbourne’s Inner North?

    Is a Buyer’s Agent Worth It in Melbourne’s Inner North?

    Is a buyer’s agent worth it? If you’re asking that question, you’ve probably already been through a few opens that went nowhere, or watched a property sell well above what you expected to pay.

    That’s usually the moment the question comes up. Not before the search starts, but somewhere in the middle of it, once the market stops feeling manageable.

    Here’s a straight answer, built on what Buyer’s Agent Victoria (BAV) actually charges and actually does, not a generic industry line.

    Buying in Melbourne’s North in the next few months? I have 3 Foundation Client places at half my standard fee. Answer 7 questions to see if you fit.

    What Does a Buyer’s Agent Actually Do?

    A buyer’s agent works only for you. At BAV, that means sourcing properties on-market and off-market, physically inspecting every shortlisted property before it reaches you, managing the negotiation, and supporting you through to settlement.

    The part that’s easy to underrate is the inspection. Jason McCall spent 12 years as an insurance property assessor and claims manager before founding BAV, reading what a building’s condition actually says rather than what an open home is styled to show. Every property a BAV client is shown has already been through that same read, not a walk-through for the listing photos.

    What Does It Actually Cost, and Is It a Commission?

    Is a buyer’s agent worth it once you look at the actual number? BAV’s Full Property Search is a flat Professional Fee of $16,500 including GST, split into four instalments across the engagement.

    That distinction matters more than it sounds. A percentage-based fee, common across this industry, quietly rewards an agent when the price goes up. A flat fee removes that incentive entirely, since the fee is identical whether the final price is $600,000 or $1,700,000.

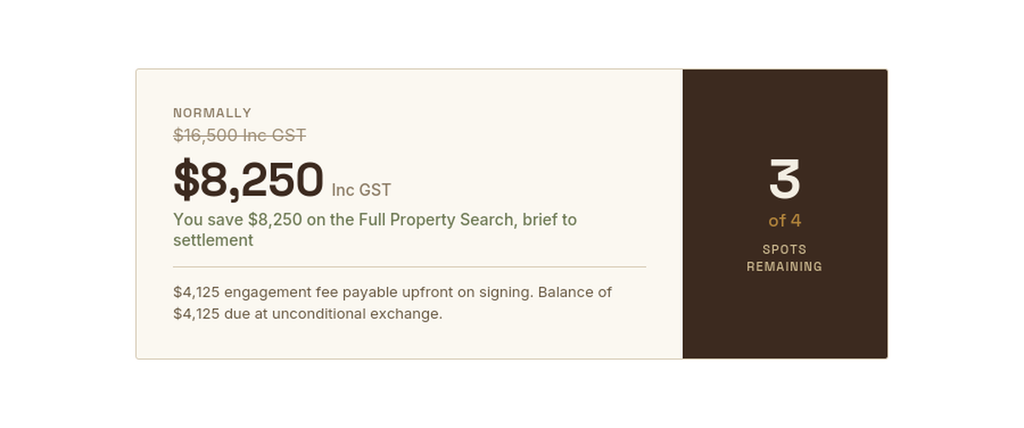
    BAV’s current Foundation Clients Offer runs the same service at $8,250 in exchange for a case study and a written testimonial after settlement, with a small number of early places still open.

    Is a buyer's agent worth it, BAV Founding Client Offer pricing card showing $8,250 discounted fee with 3 of 4 spots remaining

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.

    Where Does the Fee Actually Pay for Itself?

    Isaac B. bought his first home in Footscray as a first-time buyer working full-time shifts as a stevedore, with almost no time to search between shifts and no experience of how the process worked. BAV inspected 3 properties, and it took 14 days from engagement to an accepted offer, with the final price landing at $650,000. That was $20,000 under the $670,000 that comparable sales pointed to, and $25,000 under his $675,000 budget.

    That number matters, but Isaac’s own words afterwards were about something else entirely. He said the process “made my first property buying experience incredibly smooth and stress-free,” and that it made his life easier while working a job that left him almost no time to do any of this alone.

    A different client, Mel H., had a similar starting point in a different suburb. Five months of searching solo in Mount Clear, repeatedly outbid at auction with no access to off-market stock, before an off-market opportunity was secured on the very first inspection, $40,000 under what the comparables said the property was worth.

    What Actually Separates a Good Buyer’s Agent From an Average One?

    Two things, and neither one is really about negotiation tactics.

    The first is whether the agent physically inspects a property before you see it, or just walks it through for the listing photos. BAV treats this as non-negotiable, applying the same eye for a building’s condition that 12 years of assessing insurance claims builds.

    The second is genuine local knowledge, not a suburb researched from a desk the week before an offer goes in. Jason grew up in Thornbury and still lives there, so the streets BAV specialises in, Thornbury, Northcote, Preston and the surrounding Inner North suburbs, are known first-hand rather than looked up.

    When Might You Not Need One?

    If you already know a specific street-level market well, have negotiated a property purchase before, and genuinely have the time each week to inspect, research and follow up on listings yourself, the value of paying someone else to do it narrows.

    That’s a smaller group than the number of people who assume they’re in it, particularly first-time buyers or anyone buying in a market moving faster than they expected.

    So, Is a Buyer’s Agent Worth It?

    The honest answer depends on what getting it wrong would cost you. Getting the price wrong is expensive. Getting the property wrong is worse, because a buyer who chooses the wrong asset usually ends up selling and buying again within a few years, doing the whole process twice.

    BAV’s Full Property Search exists for exactly that reason, to get it right once, physically assessed and properly negotiated, rather than getting something that looks fine on the day and turns into a costly decision later.

    Buyer’s agents are also now formally regulated in a way they weren’t a few years ago. From 1 July 2026, buyer’s agents across Australia were classified as reporting entities under the Anti-Money Laundering and Counter-Terrorism Financing Act, meaning identity and source-of-funds checks are now a legal requirement before any engagement begins. It’s worth confirming whoever you’re considering takes that obligation seriously.

    Frequently Asked Questions

    Is a buyer’s agent worth it for a first home buyer?
    Often, yes, particularly in a competitive market where a first-time buyer is up against experienced buyers and agents who already know the local playbook. Isaac B.’s Footscray purchase is one example of that gap being closed.

    How much does a buyer’s agent cost in Melbourne?
    At BAV, the Full Property Search is a flat Professional Fee of $16,500 including GST, with no commission or success fee tied to the purchase price. Fees vary between buyer’s agents, so always confirm the fee structure in writing before engaging one. The three fee models are compared in dollars in How Much Does a Buyer’s Agent Cost in Melbourne?

    Do buyer’s agents take money from the seller?
    BAV never takes a fee from a selling agent, on any transaction. Some buyer’s agencies also run a vendor advocacy arm alongside their buyer-side work; BAV doesn’t operate one.

    Are buyer’s agents regulated in Victoria?
    Yes. Buyer’s agents operate under an estate agent’s licence issued by Consumer Affairs Victoria, and since 1 July 2026 are also classified as reporting entities under national AML/CTF law.

    Is a buyer’s agent worth it if I’ve already bought a property before?
    It depends on how well you know the specific street-level market you’re buying in now. Experience buying in one suburb doesn’t automatically transfer to a different one, particularly somewhere as local and specific as the Inner North.


    So, is a buyer’s agent worth it for your own purchase?

    Foundation Clients Offer: 3 places remaining

    I buy across Melbourne, with a focus on the North and a specialty in Northcote, Thornbury and Preston. Foundation Clients get the full property search, brief to settlement, for $8,250 instead of $16,500. In return I ask for a case study and a written testimonial after settlement.

    Answer 7 Questions to See If You Fit

    Search. Secure. Settle. On Your Side.